
Denied a home insurance claim? Get a strong appeal, drafted for you.
Upload your denial letter and we'll read it, find the strongest grounds to challenge it, and draft the reconsideration letter for you — then track every deadline and help you respond when the insurer writes back. Grounded in your actual coverage, not a generic template.
 Appeal Assistant · your honest read Example
A real appeal, start to finish.
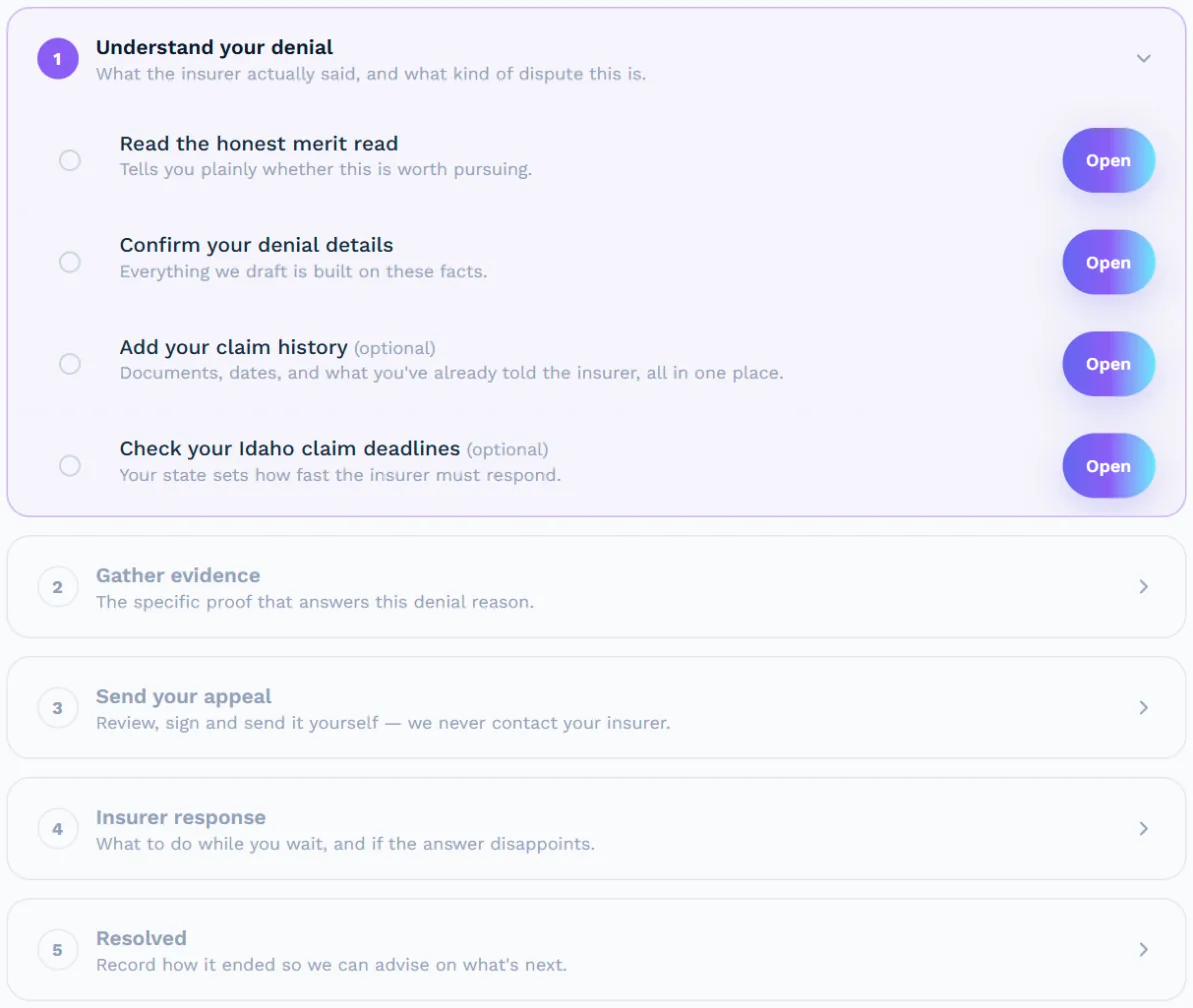
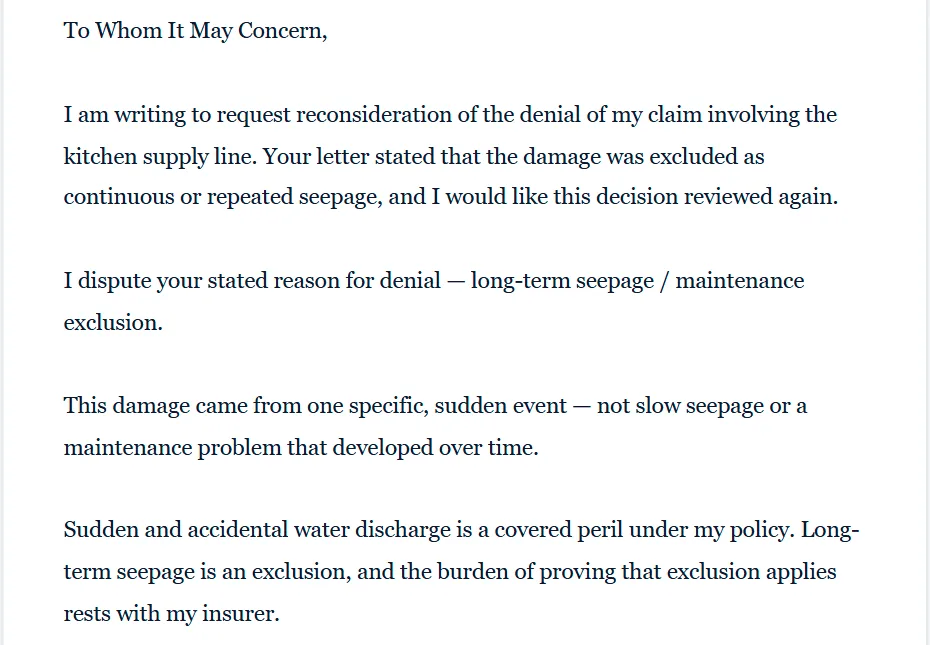
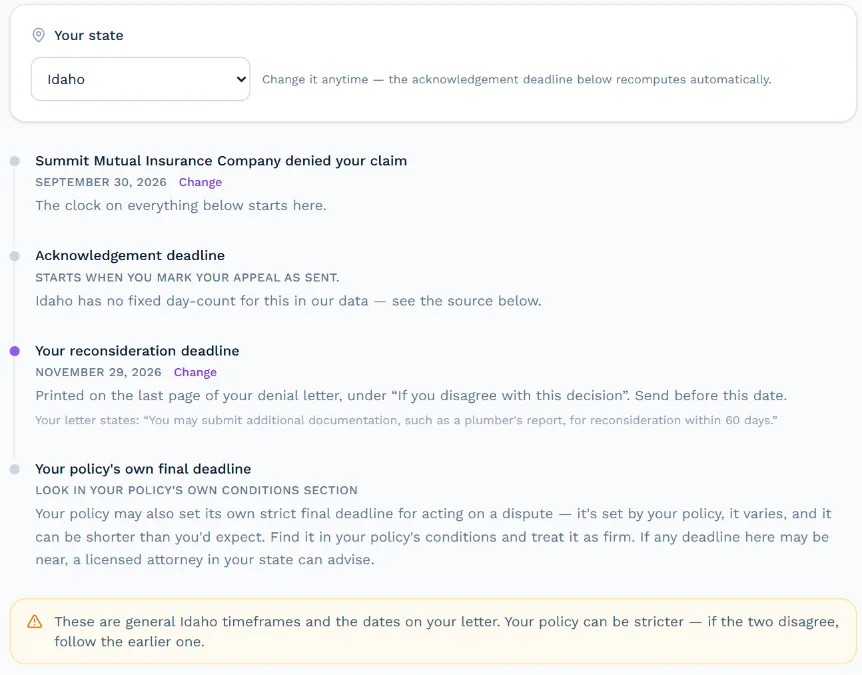
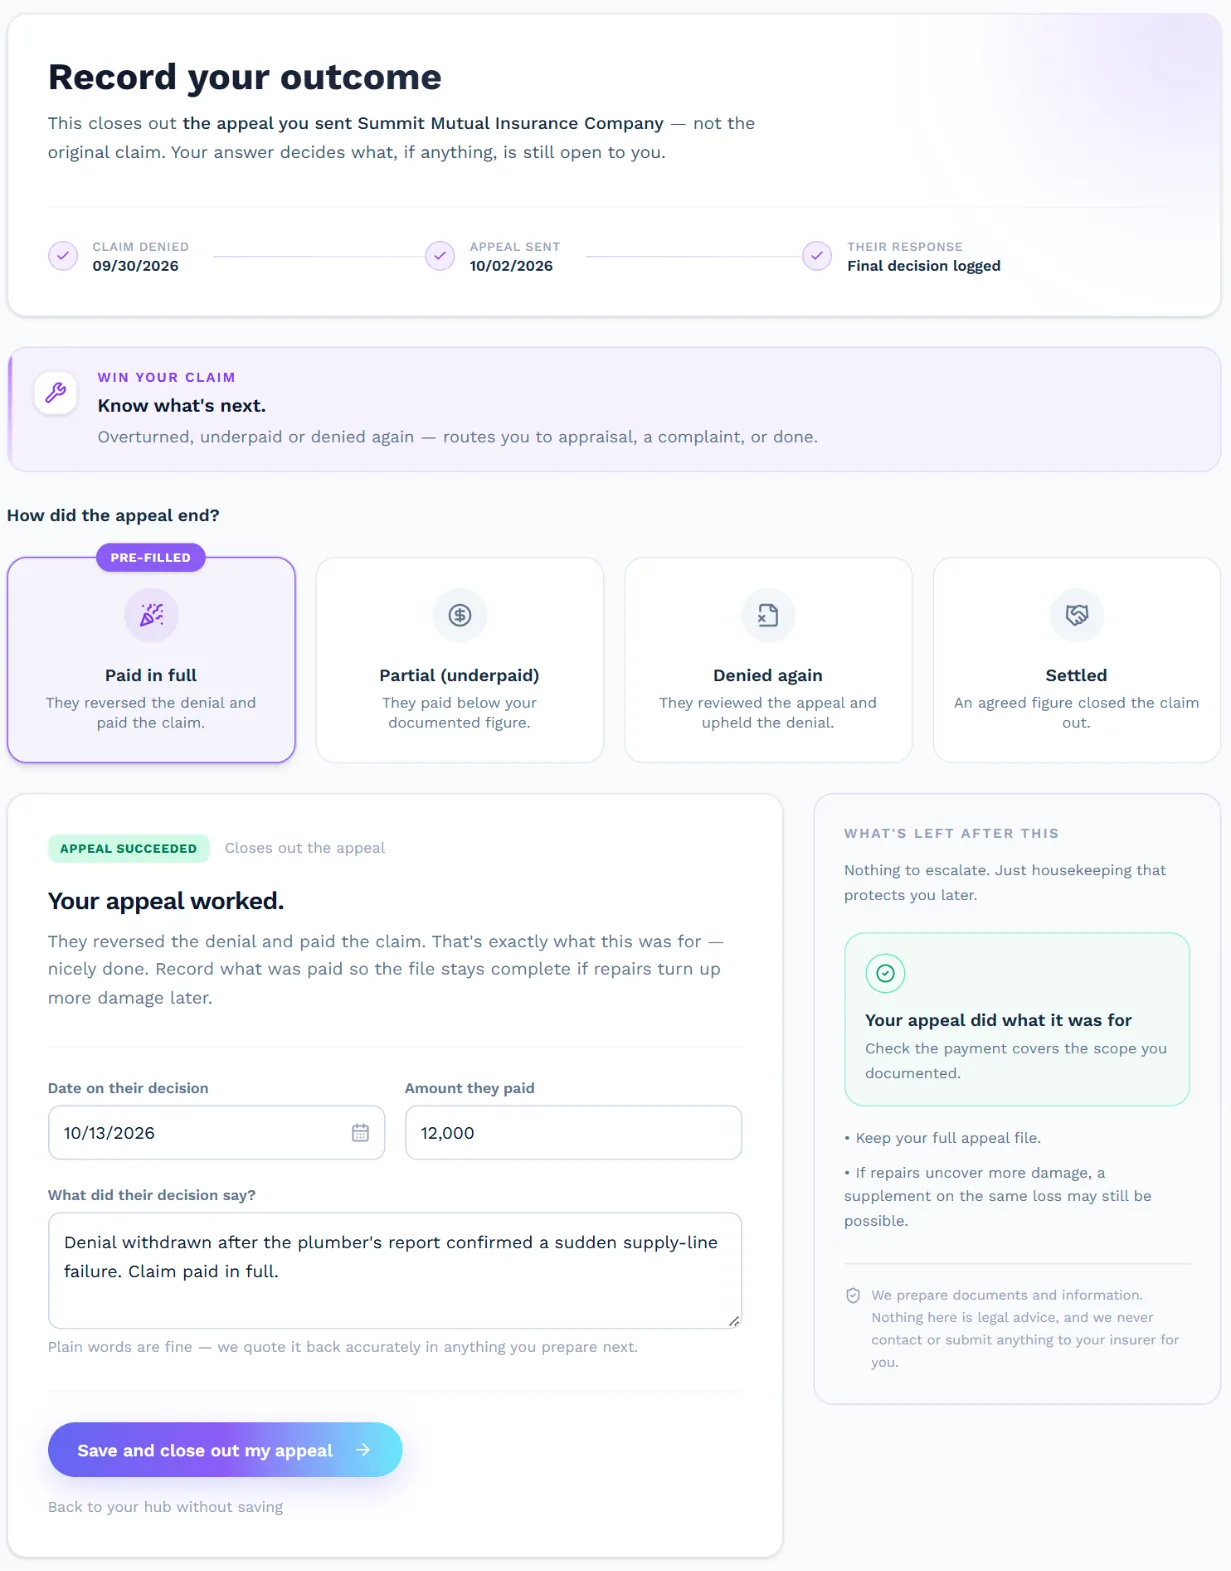
- The exact reason they gave
- The dates and your claim number
- How long you have to respond
From the denial letter to the final answer — one plan.
- An honest read on your grounds
- A letter that answers their stated reason
- Every deadline tracked
- You review and send everything yourself
From a denial letter to a strong, policy-grounded appeal.
Four steps, in plain English. You stay in control — we draft, you decide what to send.
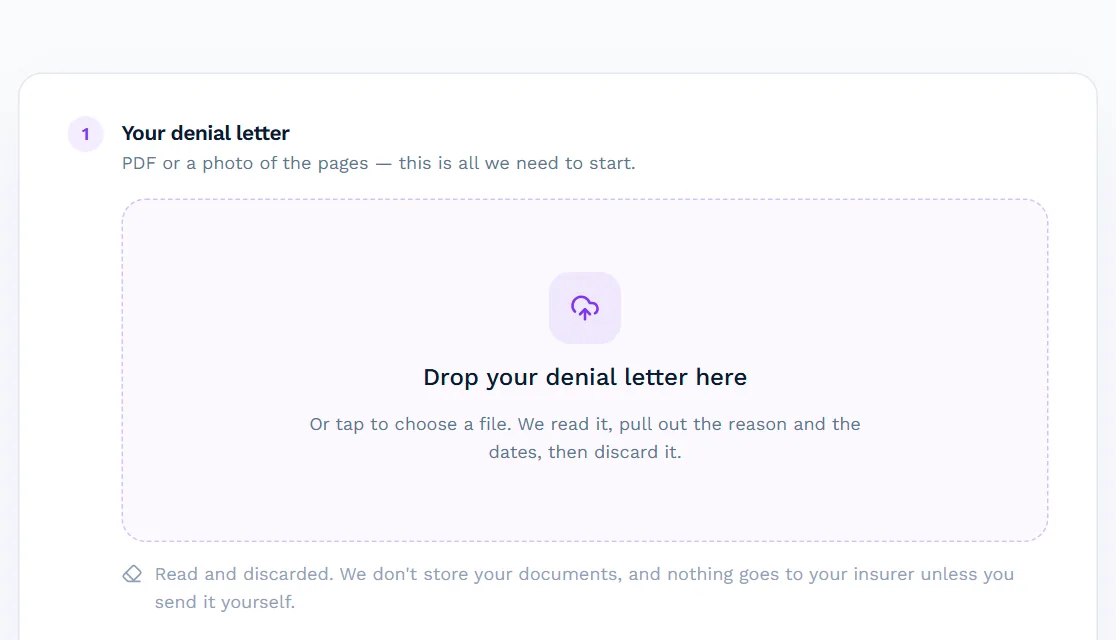
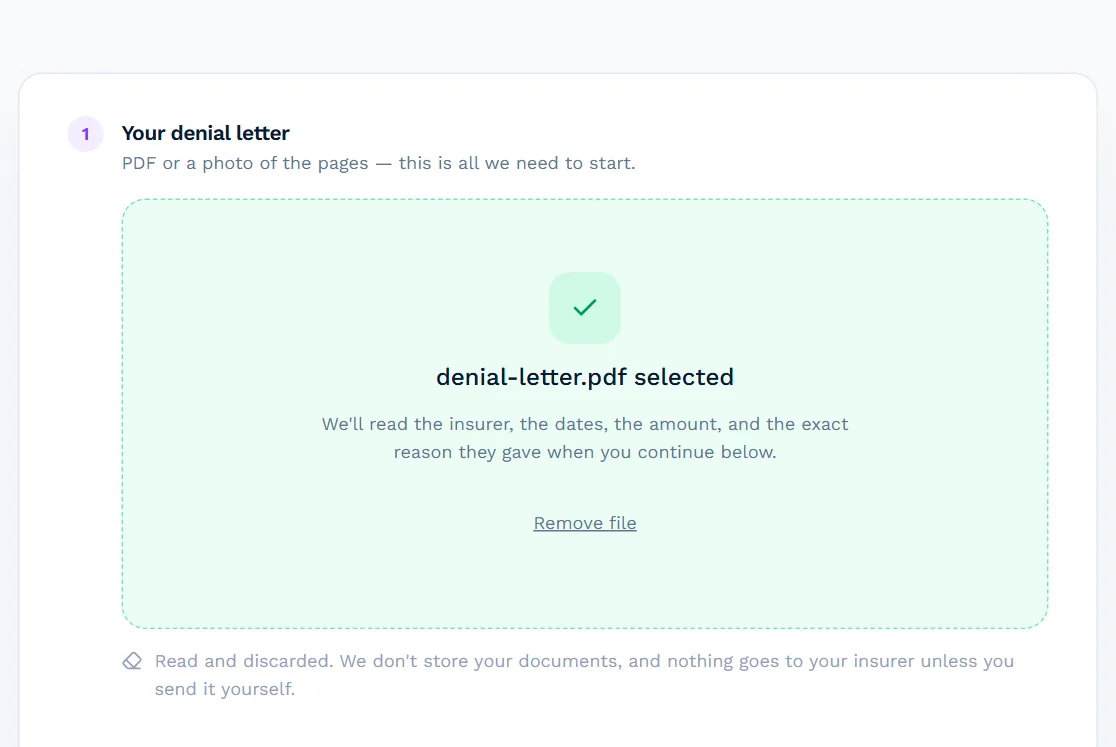
Upload your denial
Drop the denial letter — PDF or photo. We read the insurer, claim number, the reason they gave, and any deadline. Add your declarations page to sharpen the letter.
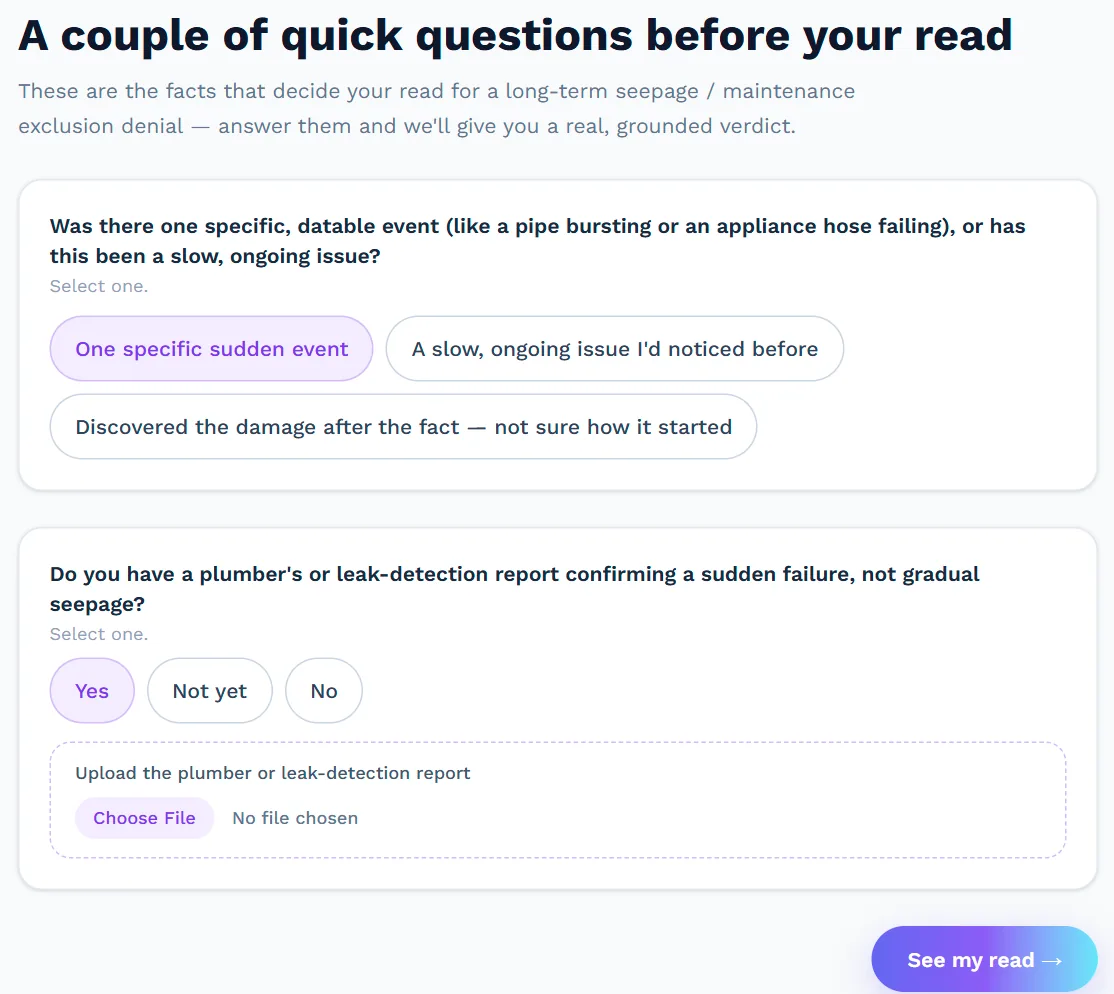
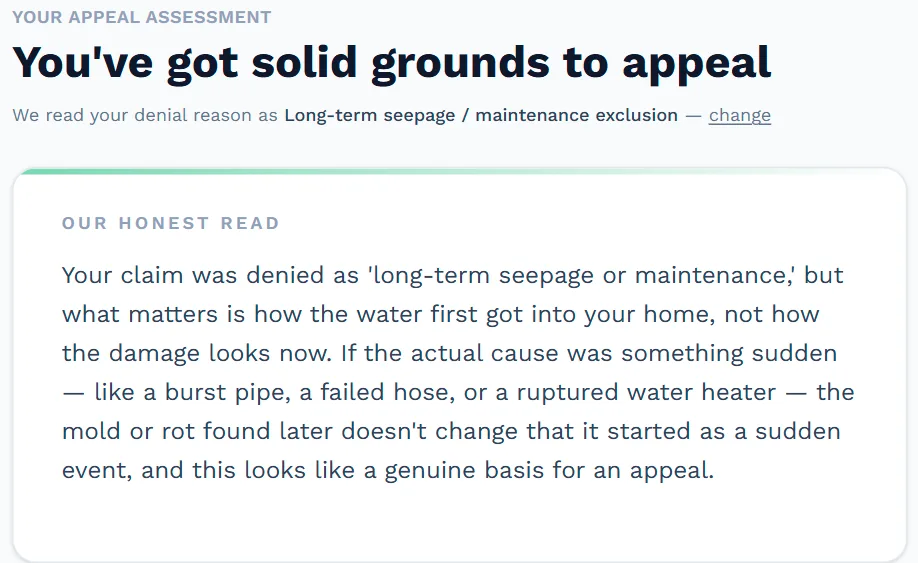
Get an honest read
Is the denial well-founded, really a dollar-amount dispute, or is there a genuine basis to challenge it? We tell you which — appealing is never the automatic answer.
Draft the appeal
A reconsideration letter built around your coverage and their exact reason — it rebuts the stated reason, won't overreach, and won't draft at all when the denial is valid.
Track & respond
Deadline and follow-up reminders, plus help responding when the insurer writes back — including appraisal or a state-regulator complaint when it's warranted.
Real help at every step of the appeal.
Is there really a case?
We never treat appealing as the default. Some denials are correct — and telling you that saves you a fight you can't win.
Built around your coverage
Grounded in your coverageA reconsideration letter that answers their exact reason with your coverage and your facts — not a template an adjuster has read a hundred times.
Follow it through
Deadlines, confirm-receipt and status-request drafts, and — when they reply — your next honest move: appraisal, a DOI complaint, or a targeted second reconsideration.
A grounded appeal beats a generic one — every time.
A template or appeal mill
- ✕ Hands you a generic letter that ignores your specific policy language
- ✕ Advertises win-rates and "we'll fight them" — promises no one can honestly keep
- ✕ Pushes every denial toward an appeal, even the well-founded ones
- ✕ Sometimes fires letters at your insurer on your behalf, out of your hands
The Appeal Assistant
- ✓ Builds every argument from your coverage and your facts, so the appeal carries weight
- ✓ Gives an honest read first — and tells you plainly when the denial holds up
- ✓ No outcome-percentage promises; your policy, insurer and state have the final say
- ✓ Nothing goes to your insurer without you — you review and send every word
A strong appeal shouldn't cost you a cut of your payout.
If a wrongful denial stands, the repair bill is yours. People pay a public adjuster or an attorney a slice of their payout to fight it. The Appeal Assistant helps you prepare a strong, grounded appeal yourself, for $99 flat, with no cut of what you recover.
You see your read before you pay anything. If the denial holds up, we'll tell you. For a large or complex dispute a professional may still be worth it.
No catch.
Will this get my appeal approved?
No one can honestly promise that. What we do is help you make the strongest, best-grounded case your policy supports — your insurer, and if needed your state regulator, have the final say. We don't advertise win-rates because they'd be meaningless for your specific claim.
What if my denial is actually valid?
We'll tell you plainly, and we won't draft an appeal designed to fail. Often we can still point to a real alternative — like a dollar-amount dispute you can take to appraisal — instead of a dead-end fight.
Do you send anything to my insurer for me?
No. We draft the letters; you review, edit, and send every one yourself. Nothing leaves under your name without you choosing to send it.
How much does it cost?
You see your read first, with no signup — whether your denial is worth challenging and how your coverage bears on it. If you go ahead, the full appeal kit (the reconsideration letter and help responding when the insurer writes back) is $99 flat. No subscription and no cut of what you recover. A public adjuster typically takes 10–20% of the payout, often $2,000–$4,000 on an average claim.
What happens to my documents?
Your denial letter and declarations page are read in transit, analyzed, and discarded — we don't store the files. If you save and track your appeal, we keep only the details you enter, never the documents.
Is this legal advice?
No — it's clear, sourced information to help you act. Your policy, your insurer, and your state are the final word. Home-insurance appeals are handled inside the insurer, so we won't promise an external review that doesn't exist for property claims.
Turn a denial into your strongest possible appeal.
Upload your denial letter for an honest read and a policy-grounded reconsideration letter you can send today. You see your read first, with no signup.
Start my appeal →